
Outer Banks flood insurance

Outer Banks flood insurance for your building and belongings

Quick answer: An Outer Banks flood policy addresses water damage that standard homeowners insurance does not cover, according to NC DOI. Start with the building address, contents, lender requirements and effective date before comparing NFIP and private options.

Source: NC DOI: flood insurance

Prepare my insurance request

Your request goes to a licensed North Carolina insurance team in Nags Head. No call centers, no lead lists, no spam.

View insurance atlas
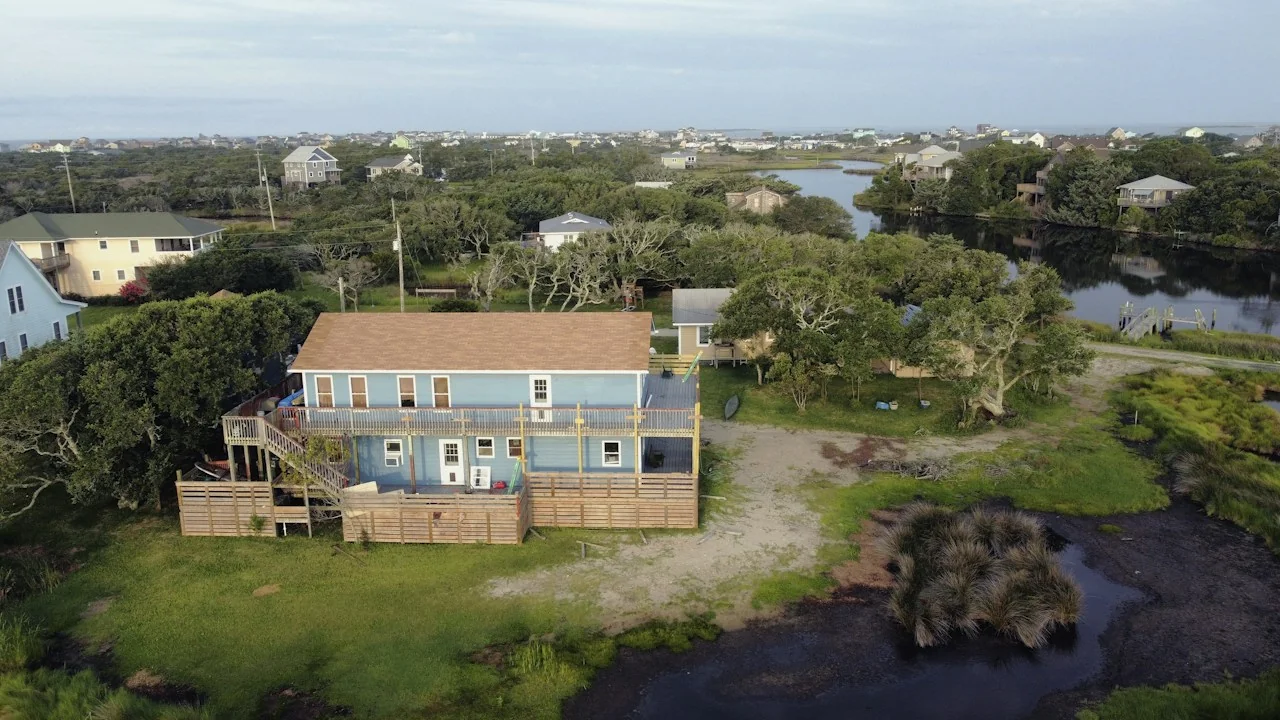
A blue coastal home with white balconies beside marsh and a pond on Hatteras Island
Coastal home · Hatteras IslandPhoto: Gene Gallin · Unsplash License

Outer Banks flood insurance addresses a different loss from ordinary homeowners coverage. Compare the building and contents protection, exclusions, deductibles and start date, then confirm what your lender requires for the address.

A little help getting started

Ask Piper

Have a question before you begin? Piper, our automated guide, helps you find your next step.

No spam. No lead selling.
No pressure parade. Just local guidance.

Understand flood protection and when it can begin.

0 of 4 checked

Check off what you have. You can start with what you know.

Building and contents are separate decisions

NFIP residential coverage offers up to $250,000 for a building and $100,000 for contents. Building and contents coverage are generally purchased separately with separate deductibles. Ask which items sit in each category and how your proposal treats belongings or equipment below an elevated floor.

Read exclusions as carefully as limits

NFIP coverage has limits on what it pays for outside the building and in basements. It does not cover additional living expenses or business interruption. If temporary housing or lost rental income concerns you, ask what another proposal actually provides; do not assume those expenses are included.

Rental-income questions

Compare an NFIP proposal with any private option

For each proposal, ask about the building and contents amounts, deductibles, excluded property, additional expenses, cancellation terms and financial responsibility of the insurer. Give the lender the proposed documents and ask whether they satisfy its requirements. A lower premium alone does not establish equivalent protection.

Confirm the effective date before a closing or storm

The NFIP generally has a 30-day waiting period. Exceptions include qualifying mortgage transactions; other limited exceptions have specific conditions. Ask the insurer to confirm your effective date and whether an exception applies. Private policy timing must be checked separately.

Closing insurance checklist

Separate flood maps from the complete risk picture

Check the effective map and ask your lender for its determination. A lower-risk zone does not mean no flood risk. Existing elevation information may help answer property questions without assuming that a new certificate is required to begin.

Flood maps and elevation certificates

Official-source context

Sources and review date

Last reviewed:

A few helpful answers

Questions about Outer Banks flood insurance

Is flood insurance required for every OBX home?

Requirements depend on the property and loan. Federally backed mortgages on buildings in high-risk flood areas generally require flood insurance; ask the lender about your specific transaction.

Can I consider flood insurance in Zone X?

Yes. A lower-risk map classification does not eliminate flood risk. Ask about available protection and the property-specific premium.

Do I need an elevation certificate before requesting information?

Usually not. Most homeowners do not need one to obtain flood insurance, although local compliance requirements can be different. Share any certificate you already have.

Can flood insurance take effect in time for my closing?

Ask the agent and lender to confirm the effective date before relying on a proposal. NFIP coverage generally has a 30-day waiting period, with exceptions for certain transactions; private policy terms vary. Provide your closing date early and have the applicable rule or exception confirmed for the actual policy.