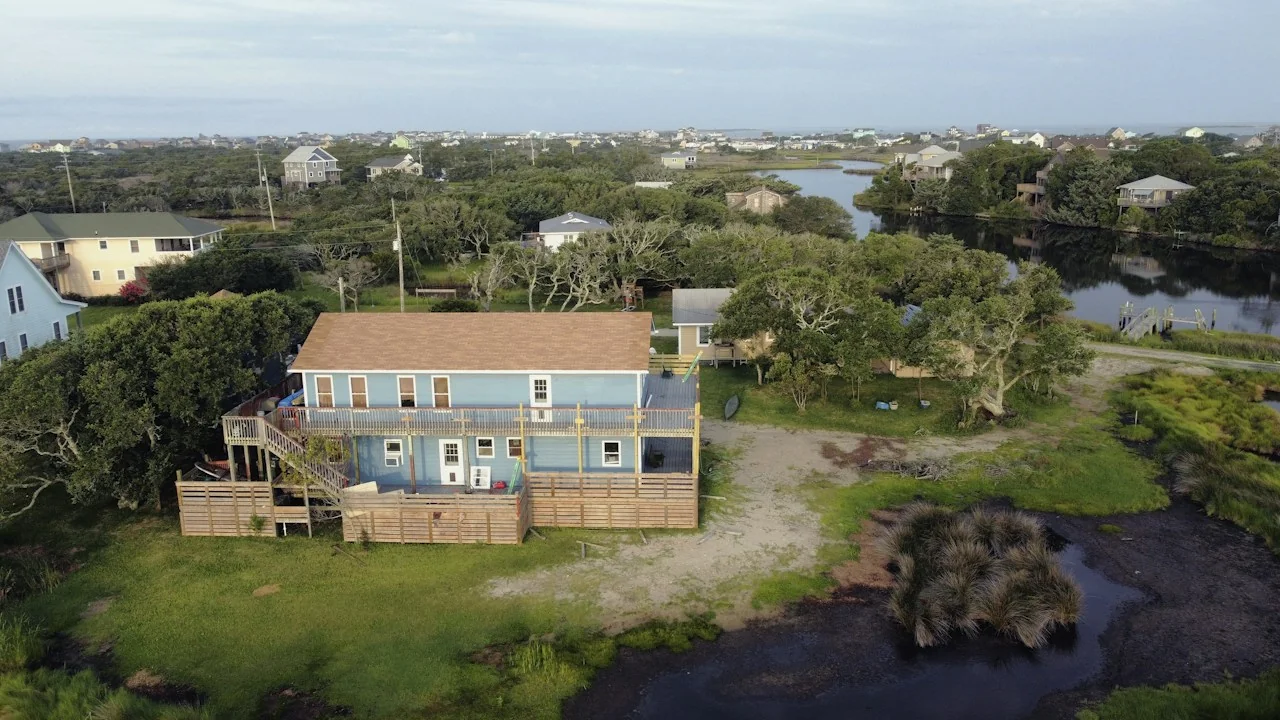
Outer Banks canalfront home insurance and waterfront features
Quick answer: For a canalfront home, inventory the house, docks, piers, bulkheads and outbuildings before requesting coverage. NC DOI describes homeowners protection for detached structures, but the policy’s exclusions and the separate flood contract must be checked for each waterfront item.
Canalfront Outer Banks property insurance questions extend beyond the house. List the bulkhead, docks, lifts and other improvements, and establish who owns or maintains each item before discussing protection.
A little help getting started
Ask Piper
Have a question before you begin? Piper, our automated guide, helps you find your next step.
No spam. No lead selling. No pressure parade. Just local guidance.
Identify waterfront property and responsibilities clearly.
0 of 4 checked
Check off what you have. You can start with what you know.
A feature’s presence on the property does not prove it is insured under the same terms as the dwelling.
01
Map ownership and maintenance responsibilities
Note whether each dock, bulkhead, walkway or lift belongs to you, an association or another party. Gather agreements and inspection records. Ask how those responsibilities affect the insurance proposal rather than treating everything as a single building.
02
Ask about damage causes and exclusions
For each structure, ask what events the contract covers and what it excludes. Have the insurer distinguish maintenance and deterioration questions from sudden damage. Request the applicable limits and deductible instead of relying on a broad description such as waterfront coverage.
03
Review water access and guest use
Explain who uses the dock and whether tenants or vacation guests have access. Identify boats or equipment that need separate discussion. Keep the house’s wind and flood documents in the same review file.
Start with the beach-house parent guide, then compare the oceanfront, soundside and canalfront checklists. Use the exact address, ownership and occupancy details to distinguish your property instead of treating a waterfront label as an insurance form.
Questions about Outer Banks canalfront home insurance
Does flood insurance automatically protect the dock or bulkhead?
+
Do not assume it does. Check the specific flood contract and ask the insurer how it treats property outside the insured building.
Should I mention shared waterfront structures?
+
Yes. Provide the ownership and maintenance agreements so responsibility can be considered accurately.
What should a canalfront inventory include beyond the house?
+
List docks, boat lifts, bulkheads and other improvements with ownership, condition and use. Identify anything shared with neighbors or an association. Ask which policy terms apply to each item and damage cause; do not assume a structure is covered because it appears in the real-estate sale.
How do I cover docks, piers, bulkheads and outbuildings on a coastal property?
+
Inventory each structure, its owner and its use, then ask the agent to identify coverage for each damage cause. FEMA’s standard flood policy excludes docks, piers and bulkheads. Detached buildings raise different questions. Request written limits and exclusions and ask whether another policy or endorsement is available for the waterfront items.