
Outer Banks oceanfront home insurance

Outer Banks oceanfront home insurance questions

Quick answer: For an oceanfront home, review the dwelling, wind terms and flood coverage separately. NC DOI explains that residential wind coverage can be excluded and purchased through a separate policy, so compare declarations rather than assuming one policy covers every coastal loss.

Source: NC DOI: windstorm and hail

Prepare my insurance request

Your request goes to a licensed North Carolina insurance team in Nags Head. No call centers, no lead lists, no spam.

View insurance atlas
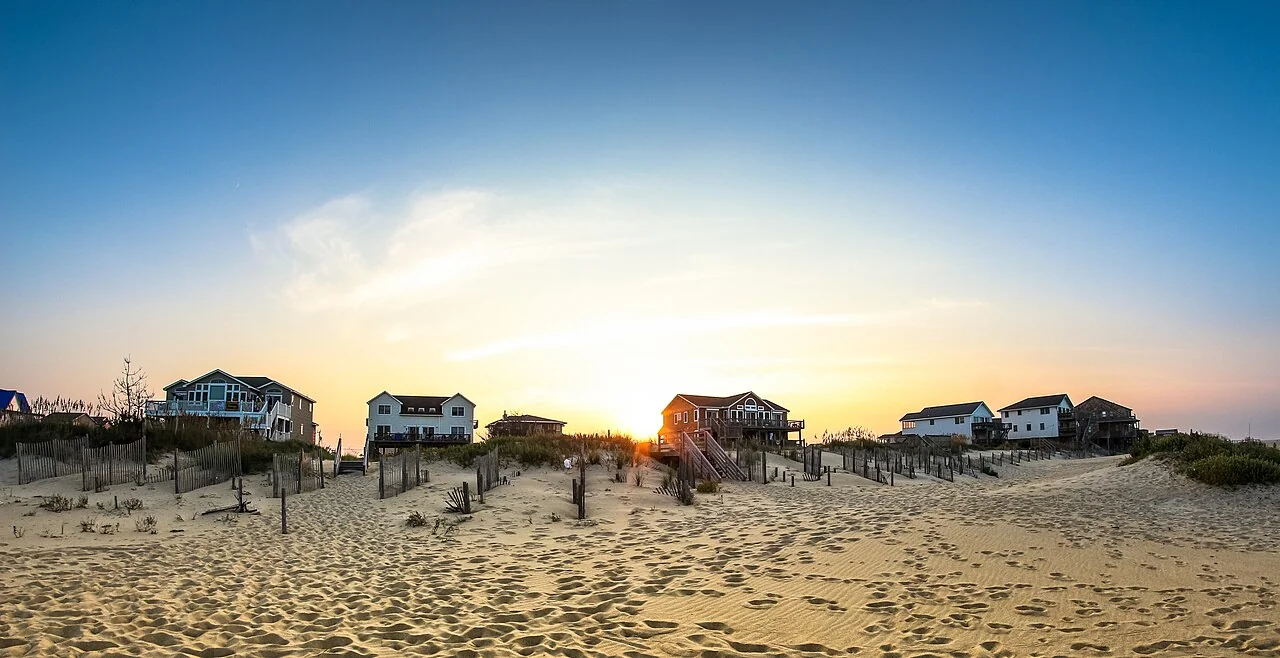
Elevated beach homes behind sand dunes at sunset in Nags Head, North Carolina
Beach homes at sunset · Nags HeadPhoto: Tim Bish · CC0

An oceanfront Outer Banks home needs a clear description of its construction, use and location. Start with the exact address and documents, then ask how the proposed insurance treats the building, coastal hazards and any rental operation.

A little help getting started

Ask Piper

Have a question before you begin? Piper, our automated guide, helps you find your next step.

No spam. No lead selling.
No pressure parade. Just local guidance.

Organize the coastal features of an oceanfront property.

0 of 4 checked

Check off what you have. You can start with what you know.

Describe the building above and below the living floor

Provide plans or inspection details for pilings, foundations, lower enclosures, decks, stairs and equipment. Identify additions and repairs. Ask the agent to explain which structures and items are included in the proposal and which need a separate discussion.

Separate rebuilding questions from the land

Discuss materials, access and the work needed to reconstruct the insured building. Ask what the policy says about ordinance or law, debris removal and excluded causes of loss. Do not assume insurance covers changes to the shoreline or the value of the land.

Read wind and flood documents together

Ask for the wind deductible in dollars, the flood limits and the effective dates. Locate any elevation record and compare it with the current building. Confirm the treatment of lower-floor equipment and belongings.

Named storm deductible examplesElevation information

Include the guests and amenities

For a rental, describe paid stays, occupancy, decks, pools and other features used by guests. Ask about liability and rental-income protection without assuming the property policy covers every interruption.

Vacation rental guide

Official-source context

Sources and review date

Last reviewed:

A few helpful answers

Questions about Outer Banks oceanfront home insurance

Does oceanfront automatically mean the same flood zone as neighboring homes?

No. Check the effective map and lender determination for the actual building.

Can a quote be based only on the listing price?

The insurer needs property information beyond the sale price. Ask how it estimates the amount needed to rebuild the insured structures.

What should I send with an oceanfront insurance request beyond the listing?

Include the inspection findings, construction details, known repairs, intended use and any available flood or elevation records. Identify the deadline and unresolved condition concerns. Ask the insurance professional what additional information is needed; a listing photograph or oceanfront label cannot establish eligibility or coverage.