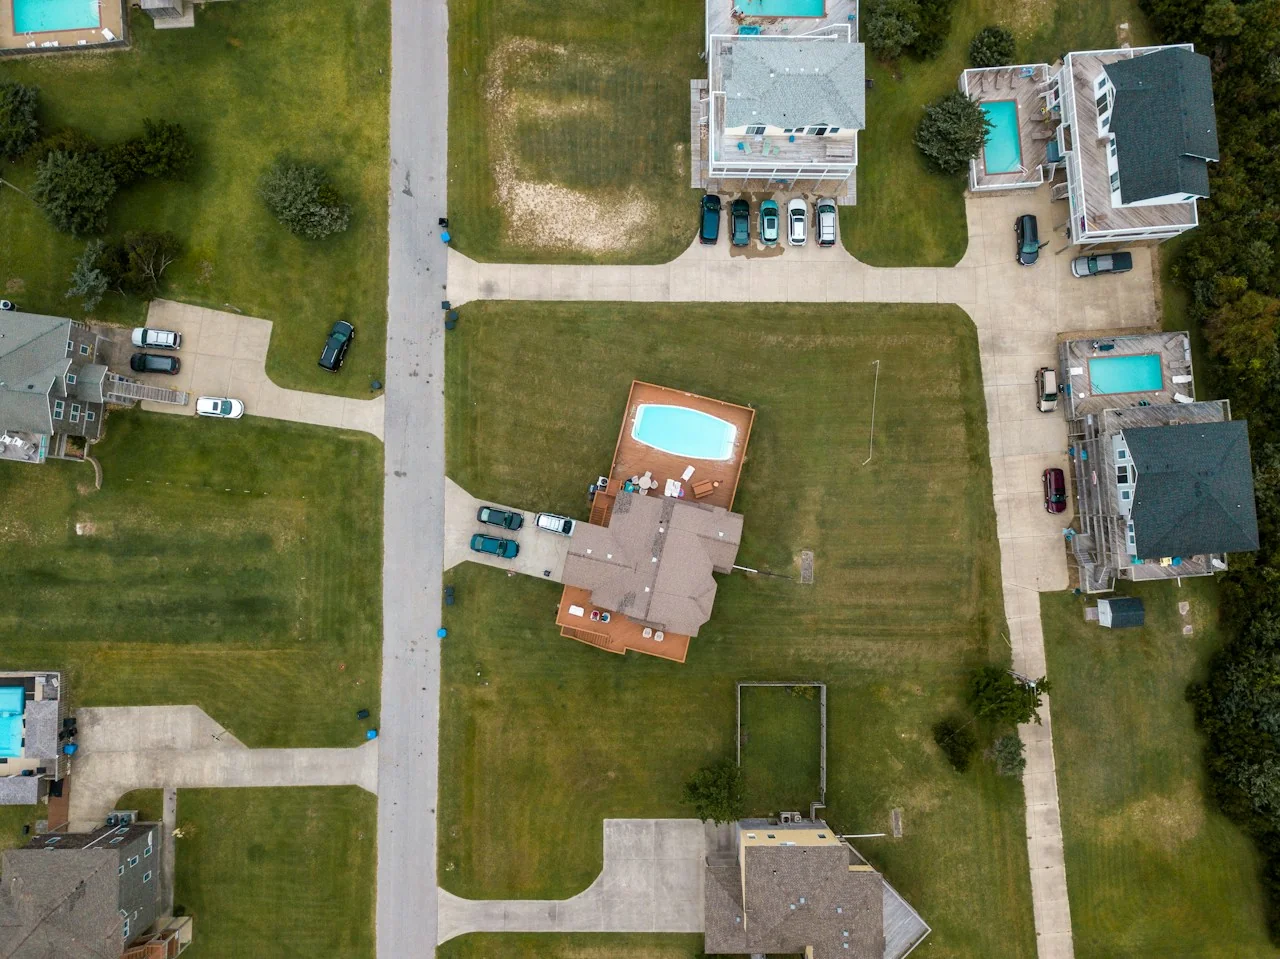
Quick answer: For Rodanthe homeowners insurance, compare the home policy with wind, flood and the property’s actual use. Dare County maintains a Hatteras Island erosion imagery map that includes Rodanthe. The county’s beach-erosion guidance documents threatened oceanfront structures; a flood-map label alone does not describe the condition of a specific oceanfront lot.
For an oceanfront Rodanthe purchase, obtain current condition reports and any notices that concern the building or site. Share them before assuming an ordinary rental-home application is sufficient. Ask distinct questions about insured damage, erosion, access interruptions and rental income; a named-storm deductible does not define every condition for a claim.
A practical checklist for a Dare County property review.
Rodanthe street address and parcel
Recent inspection and foundation information
Roof, deck and repair records
Current policies and known prior-loss details
Rental plans and furnished-property inventory
Closing deadline and lender requirements
01
What local facts matter for Rodanthe insurance?
Dare County maintains a Hatteras Island erosion imagery map that includes Rodanthe. The county’s beach-erosion guidance documents threatened oceanfront structures; a flood-map label alone does not describe the condition of a specific oceanfront lot.
For Rodanthe, request a property-specific proposal after sharing current building condition, site information and rental plans. Compare coverage exclusions and deductibles before comparing the final premium. A town-wide average would hide material differences between individual homes and is not a substitute for an underwriting review. NC DOI lists territory 110 beach-area base-rate changes of 5.1% in 2025 and 4.8% in 2026. Those percentages describe the approved rate context, not a Rodanthe quote.
Keep shoreline and building-condition questions specific
For a Rodanthe property, gather recent inspection findings, foundation information and relevant notices alongside the insurance documents. Ask how the policy treats the cause of damage, its exclusions and any conditions of eligibility. A broad description such as coastal coverage is not a promise that every shoreline-related loss is covered.
Prepare rental and rebuilding information before comparing price
Record whether the house is owner-used, rented or undergoing work. Ask how the rebuilding estimate reflects the actual structure, and identify decks, stairs, furnishings and amenities. Keep wind and flood deductibles visible and ask how the separate policies would be coordinated for the property.
Example: buying a Rodanthe rental with inspection questions
Suppose a buyer receives an inspection report identifying foundation or deck concerns. Share the report and any planned repairs before seeking a firm coverage decision. Ask what documentation or completed work is required and when coverage could take effect. A purchase contract or an online request does not establish that insurance is available.
06
Find Rodanthe parcel and flood information
Use the Rodanthe street address in Dare County's parcel and flood-map resources. The wider Tri-Villages name also includes Waves and Salvo, so keep the specific village on the document request. Ask the county about building and elevation records and verify that each record describes the actual insured structure.
For Rodanthe, request a property-specific proposal after sharing current building condition, site information and rental plans. Compare coverage exclusions and deductibles before comparing the final premium. A town-wide average would hide material differences between individual homes and is not a substitute for an underwriting review.
What should a Rodanthe owner check beyond the FEMA flood zone?
+
Use the county’s erosion guidance and Hatteras Island imagery alongside the effective flood map. Collect current inspection findings and any notices affecting the property. Ask Dare County planning about building records, and ask the agent which causes of damage the proposed home, wind and flood policies cover.
Can this website confirm insurance for a Rodanthe home?
+
No. Eligibility, quotations and binding require evaluation by a licensed insurance professional and the insurer. Provide the exact address, occupancy, construction and known condition issues for that evaluation.
Should shoreline or foundation concerns be disclosed?
+
Yes. Provide inspection findings, notices and known issues. Ask how the proposed policy treats the concern, including exclusions and any eligibility conditions, before relying on coverage.
Who will I talk to?
+
A licensed property and casualty team based in Nags Head, NC that lives and works on the Outer Banks. They can quote, explain and bind coverage; this website cannot. Your request goes to that partner team to respond to your property insurance questions.