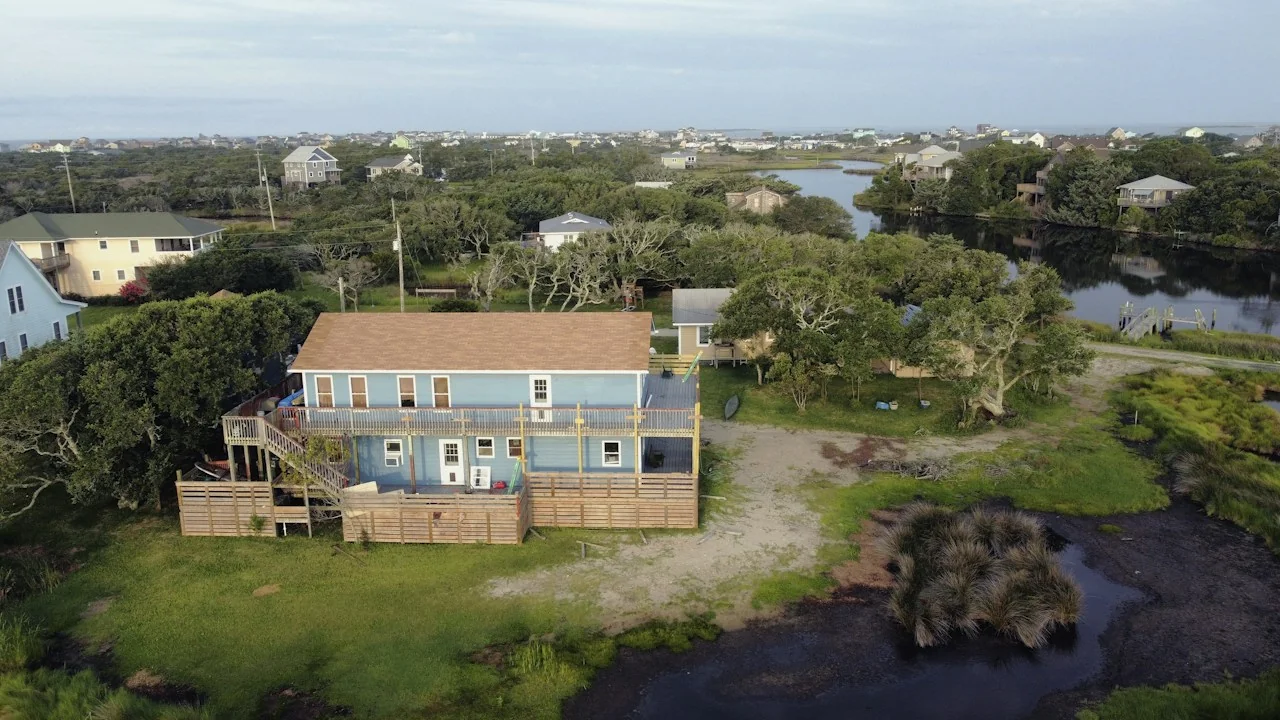
Quick answer: For Avon homeowners insurance, compare the home policy with wind, flood and the property’s actual use. Dare County reports that Avon’s 2026 beach nourishment project was completed June 25, 2026. The work is useful shoreline context, but the county project announcement does not establish an insurance discount or the coverage of any individual home.
An Avon owner can use the project map to understand the beach work near the address, then keep the insurance review focused on the insured building. List the foundation, roof, decks and paid-guest use. A soundside house also needs its own flood discussion; proximity to a nourished ocean beach does not answer that question.
A practical checklist for a Dare County property review.
Avon NC address and property use
Expiring and proposed policy declarations
Wind deductible percentages and dollar amounts
Roof settlement terms and replacement records
Flood policy and available elevation documents
Renewal dates and lender information
01
What local facts matter for Avon insurance?
Dare County reports that Avon’s 2026 beach nourishment project was completed June 25, 2026. The work is useful shoreline context, but the county project announcement does not establish an insurance discount or the coverage of any individual home.
An Avon premium comparison should identify the wind arrangement and rental occupancy on each quote. Ask whether a proposed reduction comes from a changed deductible, limit or roof settlement provision. Do not infer an individual insurance credit from the completion of the town’s beach nourishment work. NC DOI lists territory 110 beach-area base-rate changes of 5.1% in 2025 and 4.8% in 2026. Those percentages describe the approved rate context, not a Avon quote.
Make a side-by-side list of dwelling limits, other structures, belongings, liability and roof settlement terms. Add the wind and named-storm deductibles in dollars and note the effective dates of separate policies. If an insurer changes terms, ask what changed before choosing solely on the annual price.
Keep rental cottages and primary homes clearly identified
Describe whether the Avon home has year-round residents, owner visits, long-term tenants or weekly guests. Ask how the policy fits that use, including belongings and liability. If rental income matters, request an explanation of the covered events, limits and exclusions rather than assuming all missed bookings are insured.
Example: two Avon renewal options with different deductibles
Suppose an owner receives two proposals with different wind percentages. Ask for the applicable insured value and calculate the deductible dollars for each. Compare those amounts alongside roof settlement and coverage limits. This is a way to understand the options, not a recommendation to select a particular deductible.
06
Gather official Avon property information
Use Dare County's parcel and flood-map resources to identify the Avon address. Keep current inspection, roof and available elevation documents with the renewal packet. When a record is unclear or missing, ask the relevant county office or the insurance professional which document is actually needed.
An Avon premium comparison should identify the wind arrangement and rental occupancy on each quote. Ask whether a proposed reduction comes from a changed deductible, limit or roof settlement provision. Do not infer an individual insurance credit from the completion of the town’s beach nourishment work.
Does the Avon nourishment project replace a flood or elevation review?
+
No. Dare County’s June 2026 project update describes beach work, not your policy terms. Look up the Avon parcel in county GIS and NC FRIS, find any existing elevation certificate and review the actual building. Flood, wind and homeowners coverage still need to be checked separately.
How should I compare Avon homeowners insurance rates?
+
Compare equivalent property use, limits, deductibles, roof settlement and exclusions. Include separate wind and flood premiums where applicable. A lower homeowners premium alone does not describe the cost or scope of the whole arrangement.
What does a percentage wind deductible mean?
+
It is calculated using the insured amount specified by the policy, rather than simply a percentage of the repair bill. Ask which coverage amount and event trigger apply, then request the dollar figure.
Who will I talk to?
+
A licensed property and casualty team based in Nags Head, NC that lives and works on the Outer Banks. They can quote, explain and bind coverage; this website cannot. Your request goes to that partner team to respond to your property insurance questions.