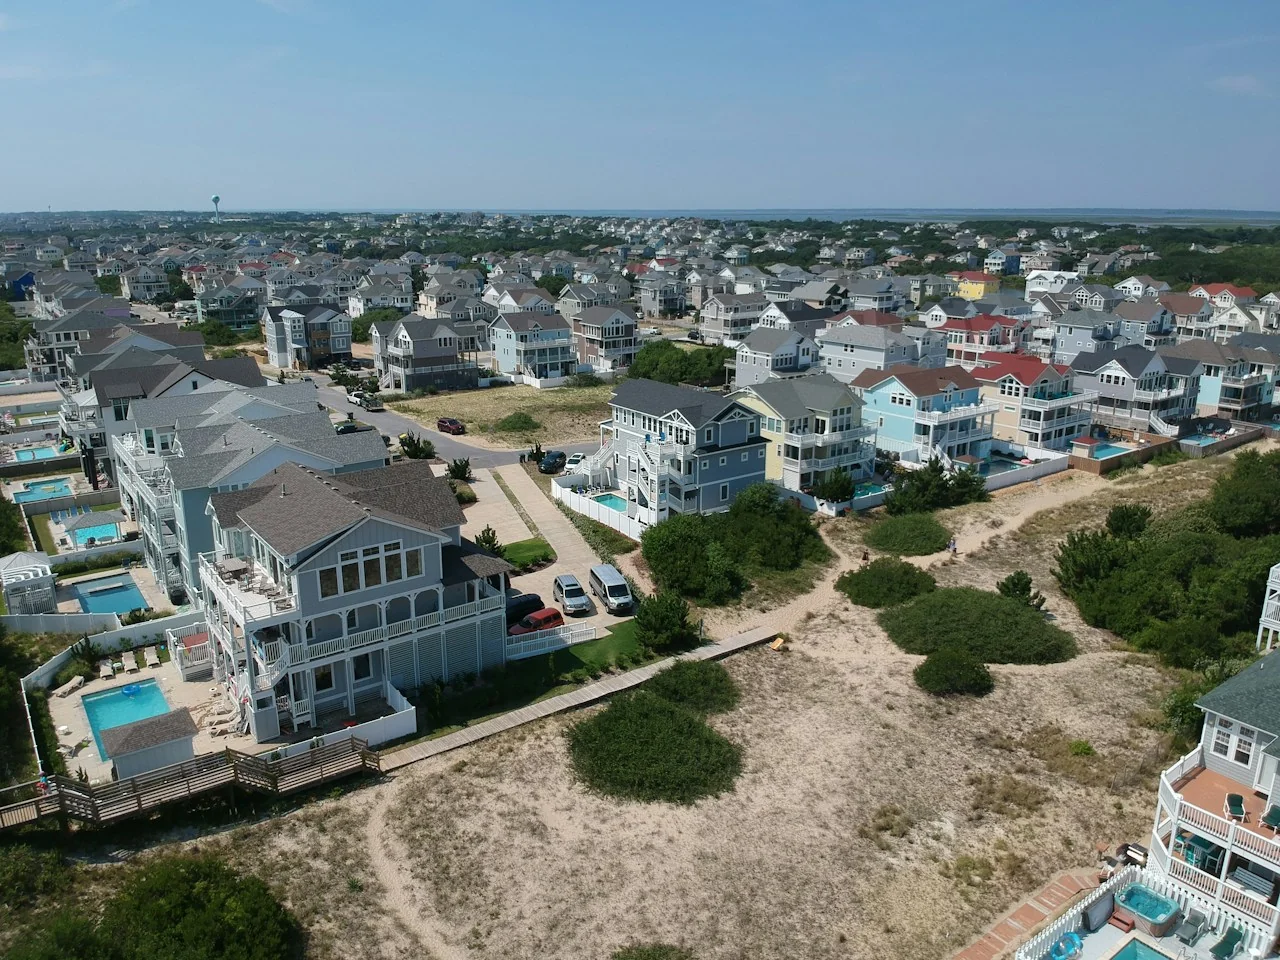
Quick answer: For Southern Shores homeowners insurance, compare the home policy with wind, flood and the property’s actual use. Southern Shores makes elevation-certificate address lists available through its Flood Protection Documents and Reports page. Copies can be requested from the town’s Planning and Code Enforcement Department.
For a second home, describe the periods when nobody stays there and who checks for leaks or damage. Identify a private dock, shared access or association-owned amenity individually. Bring the ownership documents into the review; a photograph of the waterfront does not establish which property belongs on your insurance application.
A practical checklist for a Dare County property review.
Southern Shores address and occupancy
Detached structures and waterfront improvements
Current policies and deductible details
Roof year and repairs
Available flood and elevation documents
Property-check arrangements and renewal date
01
What local facts matter for Southern Shores insurance?
Southern Shores makes elevation-certificate address lists available through its Flood Protection Documents and Reports page. Copies can be requested from the town’s Planning and Code Enforcement Department.
How much is homeowners insurance in Southern Shores?
A Southern Shores comparison should use the same rebuilding limit and occupancy assumption on each proposal. List docks and detached improvements separately before comparing premiums. Ask the agent to explain any vacancy conditions that matter when the home sits unused between visits. NC DOI lists territory 110 beach-area base-rate changes of 5.1% in 2025 and 4.8% in 2026. Those percentages describe the approved rate context, not a Southern Shores quote.
Identify structures beyond the main Southern Shores home
Create a short inventory of detached garages, sheds, decks and any waterfront improvements. Record who owns or maintains shared features. Ask which items fall under the proposed policy and which need separate attention. A broad label such as other structures does not establish coverage for every item on a property.
Describe how often you stay, whether anyone checks the home and whether friends or paying guests use it. If a second home becomes a primary residence or rental, update that description. Ask about occupancy-related conditions and any changes needed for the new use, rather than assuming the existing arrangement continues unchanged.
Example: a Southern Shores second home with a dock
Imagine reviewing a soundside second home that includes a detached shed and a private dock. Put those features on the property inventory and ask about their coverage and exclusions individually. Also describe owner visits and who checks the home between stays. The main house's insurance limit does not answer those separate questions.
06
Locate your Southern Shores property records
Dare County's parcel and flood-map resources provide a starting point for the address. For building or elevation requirements, confirm the applicable town office and records. Keep any existing certificate with your insurance documents, and ask whether further documentation is necessary for your specific purpose.
How much is homeowners insurance in Southern Shores?
+
A Southern Shores comparison should use the same rebuilding limit and occupancy assumption on each proposal. List docks and detached improvements separately before comparing premiums. Ask the agent to explain any vacancy conditions that matter when the home sits unused between visits.
Does Southern Shores keep copies of elevation certificates?
+
The town provides elevation-certificate address lists and accepts requests for copies through Planning and Code Enforcement. Match the record to the house and any later alterations. Ask whether the available document answers your current permit, lender or insurance question before paying for a new survey.
Does Southern Shores homeowners insurance cover my dock?
+
Do not assume it does. Provide the dock's details and ask about the applicable coverage, limits and exclusions. Waterfront improvements can require a different discussion from the house and its belongings.
Should I mention that the home is empty between visits?
+
Yes. Describe the actual occupancy and property-check arrangements. Ask how the policy defines and treats vacancy or unoccupancy; those terms and conditions can vary.
Who will I talk to?
+
A licensed property and casualty team based in Nags Head, NC that lives and works on the Outer Banks. They can quote, explain and bind coverage; this website cannot. Your request goes to that partner team to respond to your property insurance questions.