Provide exact location and property records
Include the parcel reference, available plans and any inspection reports. Explain the usual access arrangement and identify anything about the location that the insurer asks you to document.
Outer Banks 4x4 access home insurance
Quick answer: For a home reached by 4x4, give the agent access and rebuilding details alongside occupancy and rental plans. NC DOI describes Coverage A as protection for the house and attached structures; ask how the proposed rebuilding estimate reflects this property’s access.
Your request goes to a licensed North Carolina insurance team in Nags Head. No call centers, no lead lists, no spam.
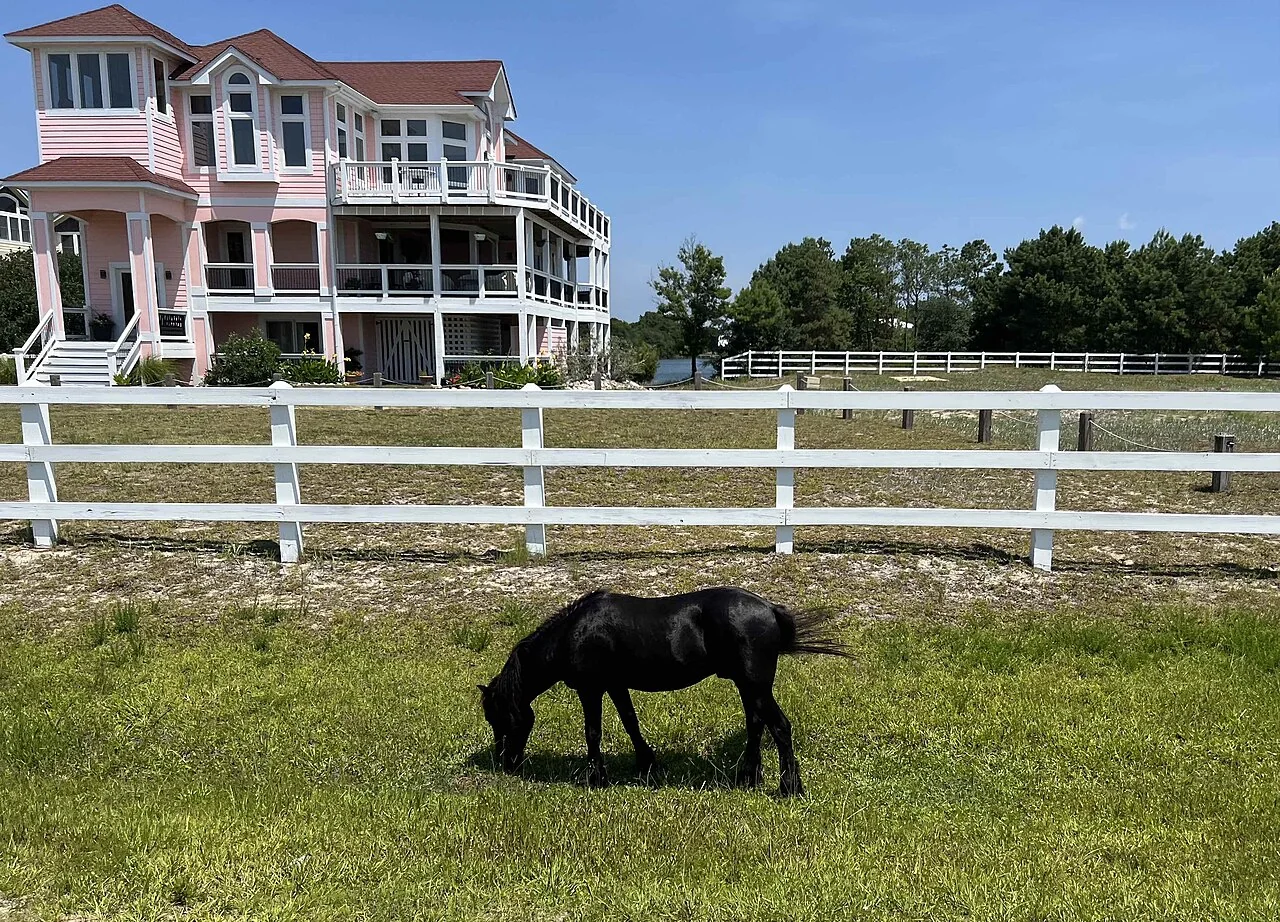
An Outer Banks home reached through the 4x4 area needs its location and access described accurately. Give the insurer the address, parcel information, construction details and intended use rather than relying only on the phrase Carova beach house.

A little help getting started
Have a question before you begin? Piper, our automated guide, helps you find your next step.
No spam. No lead selling.
No pressure parade. Just local guidance.
Check off what you have. You can start with what you know.
Access conditions raise practical questions for underwriting and rebuilding. This guide does not predict an insurer’s decision or provide travel instructions.
Include the parcel reference, available plans and any inspection reports. Explain the usual access arrangement and identify anything about the location that the insurer asks you to document.
Ask how the insurer’s estimate accounts for the building’s materials, elevated construction and delivery or contractor access. Provide roof and improvement records. Avoid using a nearby home’s insured amount as the answer for yours.
Identify who checks the house between visits or bookings and how problems are reported. For a rental, describe guest stays, amenities and management. Ask what inspections or conditions need to be satisfied before coverage can begin.
Keep the wind deductible, flood information and requested start date visible. Ask which missing documents can hold up a decision and who is responsible for obtaining them.
Official-source context
Last reviewed:
A few helpful answers
No. The insurer must review the location, property and its current underwriting requirements.
Share the address and deadline, identify missing records, and request available documents from the seller or inspection team.
Treat the other home's quote as a different property, not a price promise. Ask for a proposal using your address, access, construction and occupancy, then compare the insured amounts, exclusions and deductibles. Explain any access assumption that does not match the property before relying on the estimate.